 BTC
 ETH
 SOL
 XRP
 BNB
 DOGE
 ADA
 AVAX
 LINK
 TON
 DOT
 LTC
 TRX
 POL
 USDT
 USDC
 SUI
 HBAR
 SHIB
 BCH
 XLM
 NEAR
 APT
 ARB
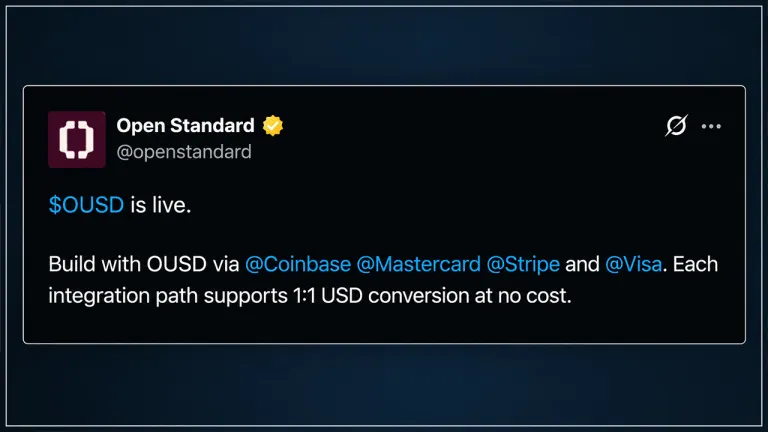
Open Standard launches OUSD stablecoin with $1bn from Visa and Mastercard partners
Open Standard's open usd (OUSD) went live on 30 September with more than $1bn committed by Coinbase, Mastercard, Shopify, Stripe and Visa, who share the reserve income.
Why it matters: The launch puts payments heavyweights behind a stablecoin that redirects reserve income to partners, challenging the issuer-keeps-the-float model used by USDT and USDC.
Key points
- OUSD launched on 30 September with over $1bn committed by five founding partners holding equal initial equity stakes.
- Tempo reported more than $400m in OUSD liquidity on its first day, with the chain targeting about $1bn within months.
Bitcoin.com News reports that the token arrived with a different economic model from existing dollar-pegged coins, with businesses able to mint and redeem it at par without fees or volume caps.
The five founders hold equal initial equity stakes, and partners are set to collect most of the income generated by the reserves rather than the issuer keeping the float. Open Standard keeps a small management fee.
The project was first unveiled on 30 June with more than 140 companies committed, a roster that had climbed above 200 by launch and includes banks, card networks and fintech firms. Tempo reported over $400m in OUSD liquidity on day one.
Open Standard still faces the question of distribution, with Bridge retaining upgrade, pause, freeze and allowlist powers and USDT and USDC holding entrenched liquidity on major venues.
Live updates on NewsFeeds:StablecoinsDesk editor: Keshav Aggarwal (accountable for this page; this summary was not edited by hand)
How this was produced: an AI model wrote this summary of Bitcoin.com News’s report, which we credit and link above. Read our Editorial and AI policy. Spotted a mistake? See Corrections.
Not investment advice. Read the risk disclaimer.